Regulatory Risk
U.S. SEC Begins Prepping for Around-the-Clock Trading That Crypto Treats as the Norm
CoinDesk reported that the U.S. Securities and Exchange Commission explored plans for around-the-clock trading during an agency event on the same morning it approved tokenized securities, a development that is not officially confirmed by regulatory filings beyond media reports.
Roundtable Discussions and Extended Hours
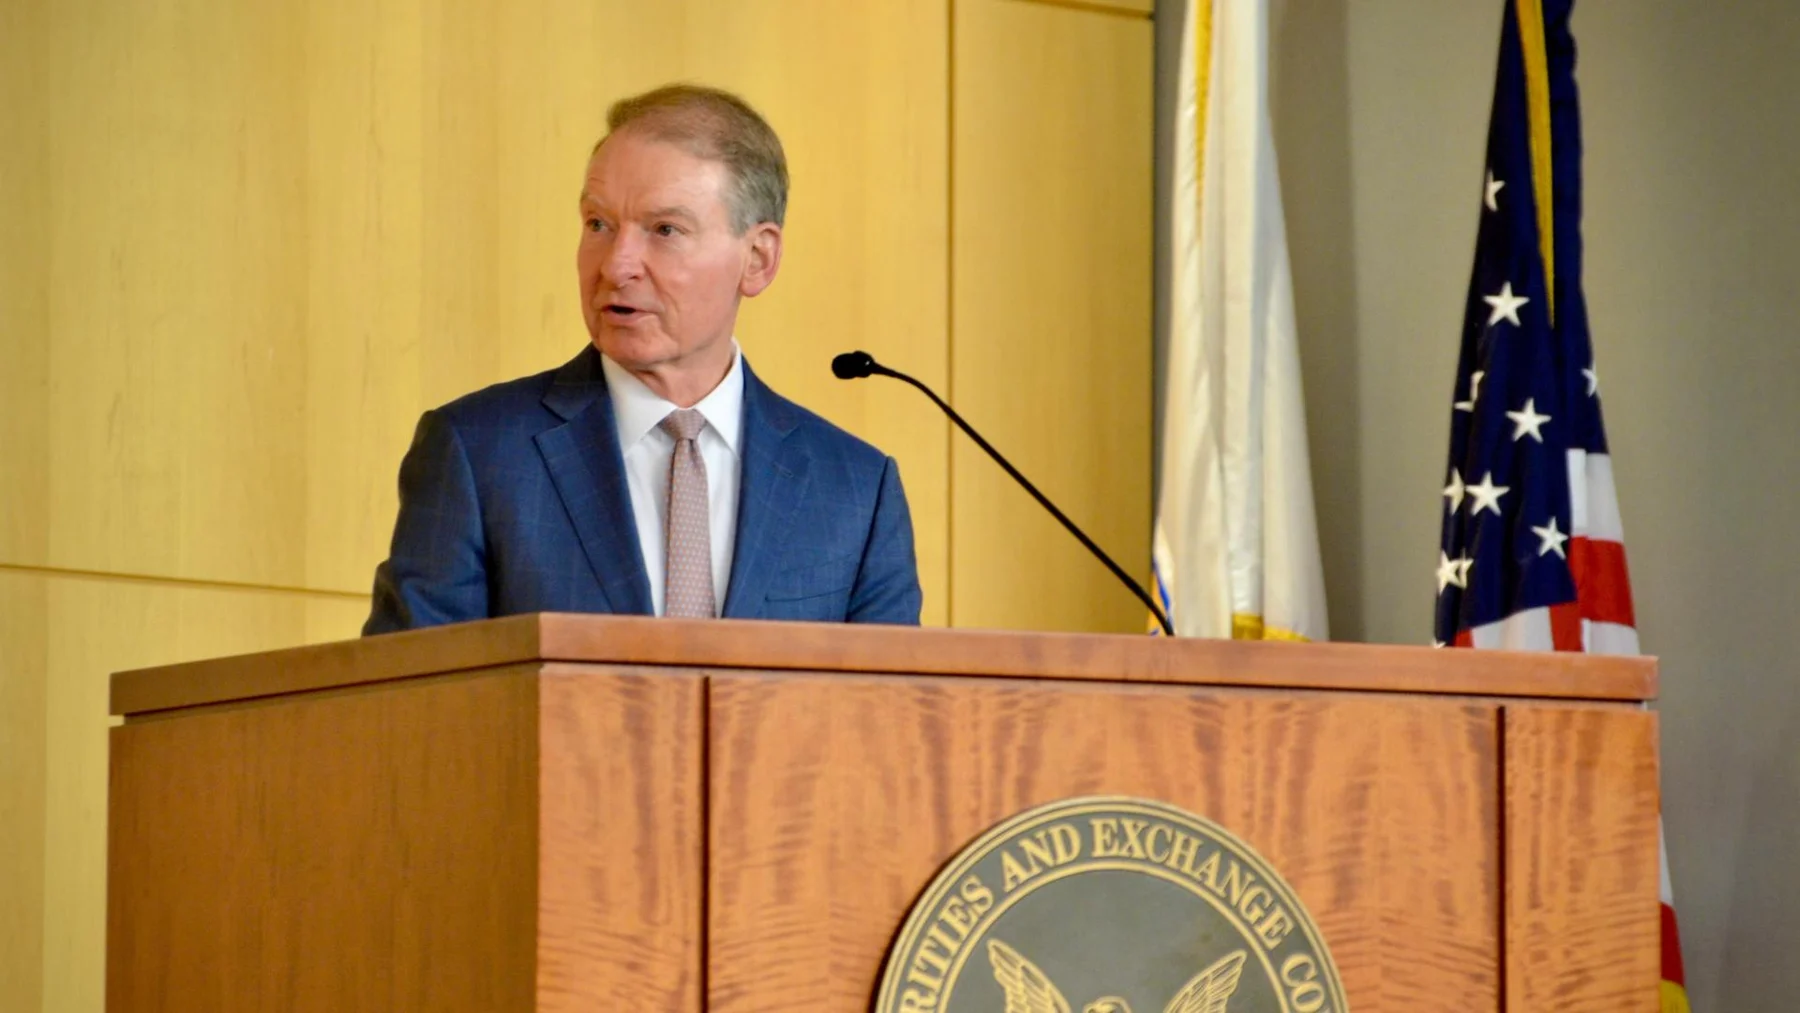
According to media coverage published by CoinDesk, the regulatory body in the United States convened a dedicated roundtable at its headquarters to investigate methods for expanding traditional market infrastructure into continuous, around-the-clock operations. This initiative mirrors the structural trading schedules that have long characterized the digital asset and cryptocurrency sectors, where trading activities proceed uninterrupted throughout weekends and holidays alike. During the proceeding, agency leadership emphasized that modern economic and corporate events do not adhere to traditional weekday office hours, suggesting that extending accessibility could empower market participants to react swiftly to breaking global developments.
Despite the stated ambitions to modernize market hours, several officials and participating market experts acknowledged that the path toward continuous traditional trading is fraught with complex logistical and technological hurdles. The transition requires comprehensive overhauls of clearing mechanisms, settlement procedures, and surveillance systems that were originally designed for discrete opening and closing bells. Furthermore, traditional financial institutions must contend with the absence of human oversight during late-night hours, raising concerns regarding how automated systems will process unexpected liquidity crunches or sudden macroeconomic shocks without immediate intervention from corporate management teams.
Tokenized Securities and Innovation Exemption
Media reports from CoinDesk also highlighted that the regulatory discussion coincided with an agency order establishing a new temporary exemption framework designed specifically for tokenized securities venues. This specialized regulatory carve-out reportedly grants a five-year grace period during which eligible firms can operate tokenized asset markets without facing the full burden of legacy regulatory requirements that traditionally govern equity exchanges. Proponents within the regulatory framework argue that incorporating distributed ledger technology into mainstream financial instruments can establish real-time inventory tracking, thereby driving operational efficiencies and reducing systemic clearing bottlenecks.
In addition to enhancing operational efficiency, the reported exemption aims to address persistent vulnerabilities within securities markets, such as settlement failures and the risks associated with abusive naked short selling practices. By facilitating a more streamlined environment for digital representations of traditional equities, the regulatory initiative seeks to harness blockchain-based transparency to eliminate settlement discrepancies entirely. However, because these policy directions and exemption details stem entirely from journalistic accounts rather than definitive administrative documents, market observers continue to analyze the precise legal boundaries and potential compliance obligations for participating entities.
Volatility and Operational Risk Concerns
The prospect of overnight and weekend trading has generated considerable debate among commissioners regarding the potential amplification of market volatility and widened bid-ask spreads during low-liquidity periods. Commissioner Hester Peirce explicitly warned that extending trading windows into hours characterized by sparse human participation could leave corporate issuers vulnerable to unverified social media rumors and overnight drama. Without dedicated corporate communications teams monitoring feeds around the clock, negative online narratives could potentially destabilize stock valuations before management has an adequate opportunity to issue clarifying statements.
Additional operational risks highlighted in the reporting include the reduced timeframe available for addressing software bugs, network outages, and technical glitches that typically require immediate engineering intervention. When trading occurs continuously, technology infrastructure operators lose the daily maintenance windows historically utilized to patch vulnerabilities and conduct system upgrades. Consequently, firms venturing into continuous operations must invest heavily in redundant systems, automated failover protocols, and robust cybersecurity defenses to ensure uninterrupted transaction processing under high-stress conditions.
Crypto Market Parallels and Structural Shifts
The ongoing dialogue within traditional regulatory circles underscores a profound structural convergence between legacy equity markets and the decentralized cryptocurrency ecosystem, which has operated on a 24/7 basis since its inception. While crypto exchanges and decentralized finance protocols treat continuous uptime as an indispensable baseline standard, traditional financial institutions are only beginning to grapple with the profound cultural and operational adjustments necessary to match this relentless pace. This divergence has historically placed traditional venues at a competitive disadvantage when responding to fast-moving geopolitical or macroeconomic events that unfold outside standard business hours.
As traditional regulators evaluate the feasibility of adopting crypto-style operational parameters, digital asset platforms may experience both indirect benefits and new competitive pressures. The mainstreaming of tokenized securities and continuous trading could legitimize blockchain-based settlement rails, fostering greater institutional adoption across the broader digital asset economy. Conversely, as traditional markets adopt features long native to crypto, digital asset exchanges will need to continue innovating in areas such as cross-border liquidity aggregation, risk management, and smart contract security to maintain their competitive edge among institutional clientele.
Conclusion and Strategic Assessment
In conclusion, media reporting from CoinDesk indicates that the U.S. Securities and Exchange Commission has initiated exploratory discussions regarding continuous around-the-clock trading while simultaneously advancing regulatory exemptions for tokenized securities. However, these reported developments remain not officially confirmed by formal administrative rulemakings or final statutory decrees published by the agency. Affected entities, including traditional exchange operators, digital asset platforms, and institutional market participants, must carefully distinguish between reported exploratory roundtable dialogues and verified regulatory mandates when evaluating their long-term compliance strategies.
Looking forward, the affected user groups and institutional stakeholders must monitor subsequent regulatory filings and official announcements from the U.S. Securities and Exchange Commission to verify whether the discussed continuous trading initiatives and innovation exemptions transition into enforceable policy. The immediate next action for institutional compliance teams is to conduct comprehensive internal reviews of their technological readiness for overnight risk management, ensuring that systems can accommodate potential structural expansions in trading hours once official confirmation becomes available.
Cexvia conclusion
Regulatory Outlook and Operational Implications
According to reporting by CoinDesk, the U.S. Securities and Exchange Commission held a roundtable to examine continuous trading schedules and approved a five-year exemption for tokenized securities, a plan that remains not officially confirmed by independent regulatory announcements.
- Risk meaning
- The transition of traditional financial markets toward continuous operations introduces structural uncertainties for digital asset platforms and institutional participants operating in global jurisdictions, potentially altering liquidity patterns and overnight risk exposures.
- User action
- Affected crypto-exchange operators and institutional participants should review their continuous liquidity management frameworks, monitor regulatory developments regarding tokenized securities, and prepare for potential operational adaptations.
Continue reading

